Kia ora,
October was the month the AI narrative finally cracked. After months of “capex is the story,” a wave of disappointing cash-flow numbers from the hyperscalers — Intel down 28%, Alphabet off 12% on a single session, Amazon’s free-cash-flow miss — sent the Nasdaq into its worst month since March 2025. Yet underneath the AI wobble, the Dow gained, defensive sectors led, and the NZX 50 quietly edged higher before surging to a fresh record in the first week of November. At home, the RBNZ delivered its own surprise — a 4-3 vote to hold the OCR at 2.75% when markets had priced in a hike — after September-quarter inflation eased to 3.7%. A busy month, and a textbook reminder that diversification across markets, sectors and styles earns its keep in exactly these conditions.
Ngā mihi,
The Athena Wealth Team
NZX 50: +0.5% in October (close ~13,830); hit a record 14,091 on 5 November.
RBNZ OCR: held at 2.75% in a 4-3 surprise vote on 28 October; next decision 9 December 2026.
Annual CPI inflation (Sep Qtr): eased to 3.7% (from 4.1%).
Best 12-month term deposit: 4.05% p.a. (BNZ / Kiwibank).
Best 1-year fixed home loan: 4.99% p.a. (ANZ / ASB / BNZ).
Global markets (NZD): S&P 500 −1.2%, Nasdaq Composite −5.2%, Dow +1.5%, Brent crude +12%.
CNN Fear & Greed Index: 22, Extreme Fear (as at 6 November 2026).
What’s happening in NZ markets
The S&P/NZX 50 ground higher in a choppy October, ending the month roughly +0.5% and closing around 13,830. Utilities, infrastructure and listed property did most of the heavy lifting as offshore tech wobbled, and defensive names benefited from a growing conviction that the RBNZ’s hiking cycle may already be done. The real fireworks came in the first week of November: on 5 November the NZX 50 jumped 2.2% to a record close of 14,091 — its best single session in nearly 19 months — after the RBNZ’s surprise hold.
The RBNZ decision was the month’s big domestic story. Stats NZ’s September-quarter CPI, released 22 October, eased to 3.7% annual (from 4.1%), keeping inflation above the 1–3% target band but heading in the right direction. With markets pricing roughly a 75% chance of a 25bp hike at the 28 October Monetary Policy Review, the Bank instead delivered a 4-3 split vote to hold the OCR at 2.75% — and markets rallied across rates, equities and the Kiwi dollar. The next decision lands on 9 December; markets now lean toward another hold.
| October snapshot · New Zealand | |
| S&P/NZX 50 (month, close ~13,830) | +0.5% |
| Official Cash Rate (RBNZ, 28 Oct hold, 4-3 vote) | 2.75% (unchanged) |
| Annual CPI inflation (Sep Qtr, released 22 Oct) | 3.7% (eased from 4.1%) |
| 12-month Term Deposit (best main-bank rate) | 4.05% p.a. (BNZ / Kiwibank) |
| 1-year fixed Home Loan rate (best main bank) | 4.99% p.a. (ANZ / ASB / BNZ) |
| NZD/USD (end October) | ~0.5631 (essentially flat) |
Rate data as at 8 November 2026. Main-bank 12-month term-deposit rates: BNZ 4.05%, Kiwibank 4.05%, ANZ 4.00%, ASB 4.00%, Westpac 4.00%. Main-bank 1-year fixed home loan specials: ANZ, ASB and BNZ at 4.99%, Kiwibank at 5.15%. Rates are subject to minimum deposit and LVR conditions; confirm with your bank before acting. Sources: termdepositrates.co.nz, interest.co.nz, RBNZ, Stats NZ.
For borrowers, the surprise RBNZ hold combined with easing CPI took some heat out of the short end of the curve. Fixed rates are now clustered tightly at the big banks — ANZ, ASB and BNZ all at 4.99% for one year — with Kiwibank sitting a little higher at 5.15%. Swap rates fell after the OCR decision, which gives wholesale lenders room to trim retail mortgage rates further, but any easing is likely to be modest with the OCR still at 2.75%.
For savers, 12-month term deposits are drifting slightly lower, with the best main-bank offers now at 4.05% (BNZ, Kiwibank) versus 4.15% at smaller institutions a month ago. If an attractive rate suits your plan, there’s a reasonable case to lock it in before the next RBNZ meeting on 9 December; equally, ‘laddering’ deposits across different maturities continues to reduce reinvestment risk if rates slide further.
Across the Tasman: RBA hikes to an 18-year high
Two central banks, two very different calls. On Melbourne Cup Day, 3 November, the Reserve Bank of Australia raised its cash rate by 25bp to 4.85% — its fifth hike of 2026 and the highest Australian cash rate in 18 years. The vote was 6-3 in favour of the increase (three members preferred to hold), and the RBA explicitly revised its inflation outlook “materially higher,” pointing to fuel prices and AI-related investment pushing up technology costs. Australian headline inflation re-accelerated to 4.3% in September and trimmed-mean inflation lifted to 3.7%, even as unemployment climbed to a five-year high of 4.7%.
For Kiwi investors, the contrast is instructive. Australian inflation is re-accelerating while ours is easing — which is why the RBNZ is sitting on its hands while the RBA is still tightening. The practical consequence is a wider NZ–AU interest-rate gap, continued pressure on the NZD/AUD cross (currently around 0.88), and higher borrowing costs for the Australian parent banks that own New Zealand’s big four. Our mortgage rates may well stay well below Australia’s for some time yet.
Investment market performance & trends
October delivered one of the sharpest sector rotations of the year. The Federal Reserve held rates at 3.75–4.00% on 28 October in a 10-2 vote (two governors dissented for a hike), and markets quickly shifted focus to the AI complex. Intel plunged 28% after weak guidance, Alphabet fell >12% on 29 October as its AI cash burn surprised the market, Nvidia dropped 4.2% and Amazon missed on free cash flow (trailing 12-month FCF reportedly −US$42bn amid aggressive AI capex). Investors are entering a “show me” phase on AI: build-out spending is now clearly visible on the P&L; the pay-off isn’t yet.
The result was a classic growth-to-defensive rotation. Nasdaq Composite fell about 5.2% (its worst month since March 2025), the S&P 500 slipped 1.2%, but the Dow Jones rose 1.5% as industrials, financials, healthcare and staples caught a bid. Oil added fuel to the inflation debate, with Brent crude up ~12% to around US$112–115/bbl. For Kiwi investors the FX layer was essentially neutral this month: the NZD/USD was almost unchanged (~0.5633 → 0.5631), so NZD-converted returns are very close to the headline local-currency numbers.
| Selected Index Returns · October 2026 (NZD terms) | |
| S&P/NZX 50 (local, NZD) | +0.5% |
| S&P 500 (US large cap) | −1.2% |
| Nasdaq Composite (US tech) | −5.2% |
| Dow Jones Industrial Average | +1.5% |
| Brent Crude Oil (price, USD) | +12% |
| NZD/USD (0.5631 end Oct) | ~0.0% (flat) |
Offshore returns shown are approximate price-based figures. Because NZD/USD was essentially unchanged over October (0.5633 → 0.5631), NZD-converted returns are close to local-currency returns this month. Sources: investinglive.com, wealthprofessional.ca, bydfi.com, interest.co.nz, Pound Sterling Live, RBNZ.
Three trends we’re watching
1. AI moves from narrative to numbers. Through 2024 and most of 2026, AI capex was the story. October was the first month investors started asking “where’s the return on it?” — and the answer, for now, is “still being built.” We’re not calling the end of the AI theme; we are saying this is the stage where concentration risk is most dangerous.
2. The rotation is doing exactly what it should. With Nasdaq −5.2% but the Dow +1.5%, broadly diversified portfolios absorbed the tech wobble surprisingly well. Industrials, financials and healthcare quietly carried the headline indices. This is diversification, not a theory on a chart — it’s the whole reason you own more than the stuff that worked last month.
3. Oil, yields, and the inflation chess game. Brent up 12% in a month is a reminder that disinflation is not a straight line. Both the Fed and the RBNZ delivered dovish surprises, but with oil pushing back up and the US 10-year still elevated, neither central bank has the luxury of claiming victory yet.
CNN Fear & Greed Index
CNN Fear & Greed Index, as at 6 November 2026 (reading of 22).
Sentiment has swung decisively. The gauge has fallen from 47 (Neutral) in early October to 31 (Fear) on 22 October, and then to 22 (Extreme Fear) this week. The AI selloff, elevated US bond yields and oil’s spike have combined to reset the mood in a hurry.
History says this is interesting. Over long samples, readings of “extreme fear” have more often marked buying opportunities than selling points. That’s not a prediction — sentiment can stay low for weeks — but for investors with cash to deploy over coming months, extreme-fear readings are the time to be calmly adding to a long-term plan, not the time to run for cover.
Behavioural finance: trends we’re seeing
A sharp mood shift — from Neutral to Extreme Fear in a matter of weeks — brings out some of the most common and expensive investor behaviours. Three stood out in October’s conversations:
Recency bias in reverse. After months of “just own the AI winners,” a handful of bad sessions had some investors asking whether the whole story is broken. The truth is usually in between: October was a healthy reset of an obvious concentration, not the end of the theme. Yet humans weight the most recent data most heavily, which is why portfolios built in euphoria often get rebuilt in panic — and vice versa.
Loss aversion on paper losses. Nobel-prize research says a loss feels roughly twice as bad as an equivalent gain feels good. When a growth-heavy portfolio drops 5% in a month, the urge to “just move it to term deposits” is strong — even though doing so locks in the loss and gives up the recovery. The uncomfortable truth: investors who sold during past “extreme fear” readings tended to miss the recovery that followed.
Herding on sentiment. When every headline, every X post and every neighbour is talking about a selloff, it feels contrarian to stay the course. It isn’t. Staying invested through a sentiment dip is the hardest thing a long-term investor does — and historically, it’s where most of the long-term outperformance is earned.
“Be fearful when others are greedy, and greedy when others are fearful.”
— Warren Buffett
What to do this month — in practice
1. Don’t act on sentiment alone. A Fear & Greed reading of 22 tells you how people feel, not what fair value is. Separate the two before making any portfolio changes.
2. Use the dip to rebalance, not to retreat. If your growth allocation drifted too high during the Nasdaq run, a small amount of selling now trims risk. If it’s drifted low after October’s drawdown, topping up at extreme-fear levels has historically been well-rewarded.
3. Keep contributing on autopilot. If you’re in KiwiSaver or regularly contributing to managed funds, your automatic contributions are buying at lower prices this month. That’s a feature, not a bug.
What’s new at Athena Wealth
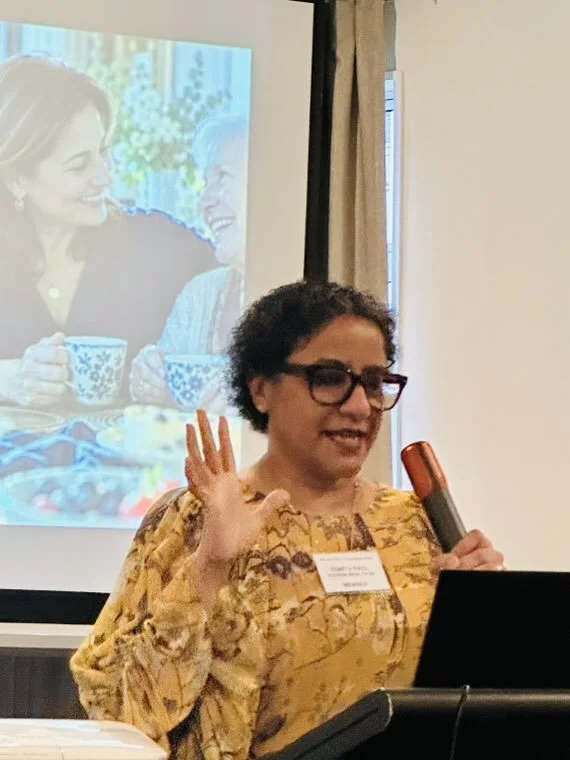
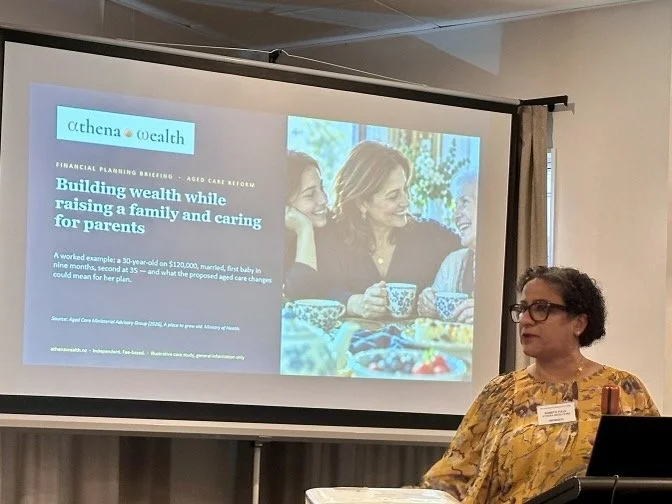
Sumita on the Auckland Executive Club stage: “Living Longer”
Thank you to everyone who came along to the Auckland Executive Club’s October dinner meeting, where Sumita delivered her Member Spotlight — “Living Longer: Aging, Health Care and What It Means for Women.” The conversation ranged from the practical cost of growing older in Aotearoa to the decisions women often end up making alone later in life, and the response in the room was genuinely heartening.
For clients and friends who couldn’t make it, the two blog posts below pick up exactly where the talk left off.
Care costs in retirement: what could change for a couple on NZ Super
The Ministerial Advisory Group on Aged Care handed the Government its report “A Place to Grow Old: Securing the Future of Aged Care” earlier this year, and the recommendations — if adopted — would materially change what Kiwi retirees can expect to contribute toward their own residential and in-home care. These are proposals, not law yet, but the direction of travel is clear.
Our new blog walks a worked example through the numbers: a couple aged 65 and 69 with a $1.5m Auckland home and $500,000 invested, and what the proposed reforms could mean for their budget over the next two decades.
Read: Care costs in retirement →When Life Shakes
Drawing on Bruce Feiler’s research into “lifequakes” — the large, often-forced transitions that reshape our lives — this piece looks at why good financial planning has to work on both the money side and the emotional side of change, and why that matters especially for women navigating divorce, bereavement, career shifts or health events later in life.
Read: When Life Shakes →Looking ahead
The calendar is dominated by two central-bank meetings landing within a day of each other. The US Fed meets 8–9 December, and a Reuters poll has 100 out of 100 economists expecting a rate increase — a rare unanimous call that itself deserves a healthy dose of September’s humility. The RBNZ’s next OCR decision is also on 9 December; after October’s surprise hold and easing CPI, markets lean toward another hold, with the first possible cut not expected until early 2027. Earnings season also keeps feeding the AI debate; expect more volatility, and plenty of opportunity for a disciplined plan to earn its keep.
If anything in this month’s update prompts a question — about your risk profile, your KiwiSaver settings, your mortgage strategy, or how extreme-fear readings fit your plan — please get in touch. We love hearing from you.
Aegis Returns · Athena Wealth, Aotearoa New Zealand
sumita@athenawealth.nz · Member home
Disclaimer: This article is general information only and does not constitute personalised financial advice. Investment involves risk and past performance is not a reliable guide to future returns. Information is sourced from publicly available data including interest.co.nz, termdepositrates.co.nz, RBNZ, Stats NZ, NZX, Investing.com, CNBC, Pound Sterling Live, CNN Business and other financial publications as at the date of issue. All offshore returns are converted to New Zealand dollars where indicated. Please contact us before acting on any of the information contained here. © 2026 Athena Wealth.
Sumita speaking at Auckland Executive Club, 20 October 2026