
Why Didn't My Mortgage Rate Drop When the OCR Fell?
A NZ financial planner reads the FMA's new bank data
Most of us have had the same quiet thought while watching the news. The Reserve Bank moves the Official Cash Rate, the headlines announce it, and then not much seems to change on our own mortgage statement or in our savings account. Until recently there was no way to check whether that feeling was accurate. Now there is!
Since August 2025, the Financial Markets Authority has published a table showing exactly when and by how much New Zealand's eight largest banks change their floating mortgage and on-call savings rates after every OCR review. ANZ, ASB, BNZ, Co-operative Bank, Kiwibank, SBS, TSB and Westpac — together around 98% of New Zealand home lending. Named, dated, and updated seven days after each Reserve Bank decision.
It came out of Parliament's banking inquiry, where FMA told MPs that the time banks took to pass on OCR changes was something the regulator would watch closely. Most New Zealanders still don't know it exists.
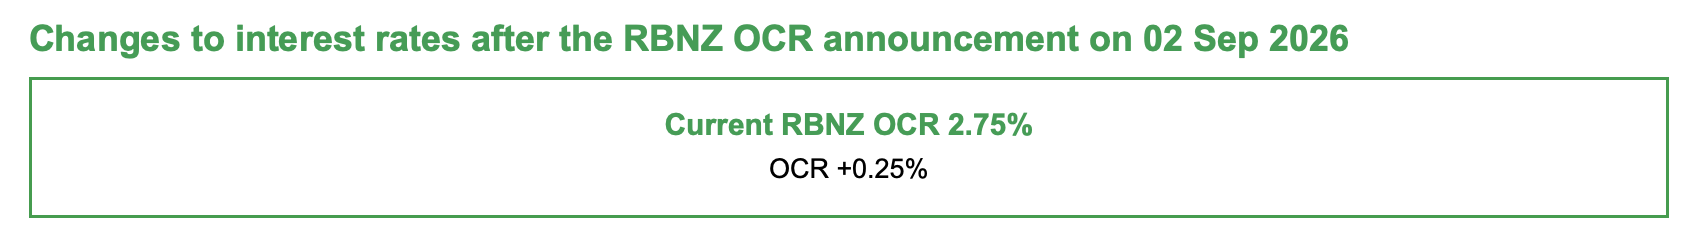
Find the FMA's OCR Pass Through Transparency table at fma.govt.nz.
Here is what it shows.
1. The OCR fell further than your mortgage rate did
In August 2025 the OCR was 3.25%. Today it is 2.75% — half a percentage point lower.
Over the same period, floating mortgage rates fell by between 0.10% and 0.26%, depending on the bank. The difference didn't disappear. It widened the gap between what banks pay for money and what they charge for it.
No single announcement would ever have shown you that. It is only visible because someone is now keeping a running record.
2. Rates rise like rockets and fall like feathers
On the way down, between August and December 2025, banks passed on roughly 60% to 96% of the OCR cut to floating mortgages.
On the way up, after the September 2026 rise, every single bank passed on the full 0.25% or more.
Economists call this rockets and feathers. It's well documented in petrol markets internationally. This is the first time New Zealand households have been able to watch it in their own banking market.
3. The savings gap is where the real money is
After that same September 2026 review, on-call savings rates across the eight banks ranged from 1.90% at the top to 0.25% at the bottom. Two banks passed on none of the OCR rise to savers at all, while passing the full increase to borrowers.
On a $20,000 emergency fund, that spread is worth about $330 a year, before tax — for doing nothing except holding the money somewhere else.
We see this constantly. People will spend an hour comparing power companies, then leave an emergency fund at 0.25% for four years because nobody ever told them to look. That is not a failure of discipline. It is a failure of visibility.
What to do this week
Check your actual savings rate. Not the advertised headline — the real rate on your real account, in your internet banking. There is currently about 1.65 percentage points between the best and worst on-call rates available.
If you have a floating mortgage, ask two questions. What rate am I on, and when does a change take effect for me as an existing customer? New customers almost always see new rates first. You now have public evidence of what the other seven banks do.
Don't switch on this alone. Your fixed-rate arrangements, cashback claw-backs, offset accounts and break costs all matter more than a few days of timing. Use this as evidence for a conversation, not as a decision in itself.
Build it into a rhythm. The table sits on the FMA website under Reports and Papers, updated seven days after each Reserve Bank review. Five minutes, quarterly.
Final thought
The FMA cannot make a bank lower your rate, and it has said so plainly. What it can do is make behaviour visible — and visible behaviour has a way of improving. That only works if people actually look.
You are not bad with money for never having seen this data. Almost nobody has. But now you know it exists, and knowing where to look is most of the work.
Find the FMA's OCR Pass Through Transparency table at fma.govt.nz.
Athena Wealth is an independent, fee-based financial planning practice in New Zealand, committed to helping New Zealanders make informed decisions and build lasting financial security. We do not sell banking products and receive no commissions from banks. If you'd like to talk through how your cash, mortgage and investments fit together as one plan, book an initial chat.
This article is general information only and is not personalised financial advice. It is based on data published by the Financial Markets Authority and is current at the date of writing. Interest rates change frequently — always confirm current rates directly with the provider before acting. Please seek advice from a licensed financial adviser before making changes to your mortgage or savings arrangements.